Key takeaways
- About 5,900 homes were sold in Abu Dhabi City in Q3 2026, 7.5% fewer than a year earlier, for AED 26.4 billion, 39.2% more.
- Apartment deals fell 31.1% as fewer towers were launched; villa and townhouse deals rose 89.4% on new off-plan launches.
- Al Reem and Yas took 60.6% of apartment sales; Al Hudayriyat took 45.5% of villa sales.
- Prices keep rising, but more slowly: apartments +11%, villas +8.9%; rents +3.5% and +1.8% under the rental freeze.
- About 14,600 homes are due in 2027 and 24,200 in 2028, though past delivery rates suggest part will slip.
Abu Dhabi City closed the third quarter of 2026 with fewer home sales and more money changing hands. About 5,900 residential units were sold between July and September, 7.5% fewer than a year earlier, while the value of those sales rose 39.2% to AED 26.4 billion (about $7.2 billion). Buyers did not leave; they moved to bigger and more expensive homes, mostly off-plan villas and townhouses.
Below is what the figures of the quarter say about sales, prices, rents and new supply, and what they mean if you are buying, selling or renting in the capital. The full report with every chart is free to download at the end of the article.
The quarter in two numbers
- 5,900residential unit sales in Abu Dhabi City, −7.5% year on yearQ3 2026 · Cavendish Maxwell, Quanta
- 26.4AED bnvalue of residential sales, +39.2% year on yearQ3 2026 · Cavendish Maxwell, Quanta
Volumes fell for the third quarter in a row, from 8,300 deals at the end of 2025 to 5,900 now. Value fell too against the record first quarter of 2026 (AED 38 billion), but it is still above the first three quarters of 2025. Fewer deals for more money means the average ticket grew: the mix of what is bought has changed.
Switch the chart between all deals, apartments, villas and value to see where the change comes from. Hover over or tap a column for the split between off-plan and ready homes.
- 3.6k2.5k1.1k12.2 bnQ1 25Q1 25Off-plan 2.3k · Ready 1.3kQ1 25Off-plan 1.6k · Ready 0.8kQ1 25Off-plan 0.7k · Ready 0.4kQ1 25Off-plan 9 bn · Ready 3.3 bn
- 3.9k2.7k1.1k11.6 bnQ2 25Q2 25Off-plan 2.3k · Ready 1.6kQ2 25Off-plan 1.6k · Ready 1.2kQ2 25Off-plan 0.7k · Ready 0.5kQ2 25Off-plan 7.7 bn · Ready 3.9 bn
- 6.3k5.1k1.3k19 bnQ3 25Q3 25Off-plan 4.5k · Ready 1.8kQ3 25Off-plan 3.7k · Ready 1.4kQ3 25Off-plan 0.8k · Ready 0.5kQ3 25Off-plan 14.7 bn · Ready 4.3 bn
- 8.3k4.6k3.8k27.9 bnQ4 25Q4 25Off-plan 6.6k · Ready 1.7kQ4 25Off-plan 3.3k · Ready 1.3kQ4 25Off-plan 3.4k · Ready 0.4kQ4 25Off-plan 23.2 bn · Ready 4.6 bn
- 8.1k5.7k2.4k38 bnQ1 26Q1 26Off-plan 6.6k · Ready 1.5kQ1 26Off-plan 4.6k · Ready 1.1kQ1 26Off-plan 2k · Ready 0.4kQ1 26Off-plan 33.9 bn · Ready 4.1 bn
- 7.3k5.7k1.7k29.6 bnQ2 26Q2 26Off-plan 6.1k · Ready 1.2kQ2 26Off-plan 4.9k · Ready 0.8kQ2 26Off-plan 1.3k · Ready 0.4kQ2 26Off-plan 26.2 bn · Ready 3.4 bn
- 5.9k3.5k2.4k26.4 bnQ3 26Q3 26Off-plan 4.7k · Ready 1.2kQ3 26Off-plan 2.7k · Ready 0.8kQ3 26Off-plan 2k · Ready 0.4kQ3 26Off-plan 23.3 bn · Ready 3.1 bn
Cavendish Maxwell, Quanta. Thousands of deals; value in AED billion
Off-plan still carries the market: about 4,700 of the 5,900 deals and AED 23.3 billion of the AED 26.4 billion. Its growth, however, has slowed from 185% and 175% year on year in the first two quarters to 4% in the third, as registration lags from 2025 launches unwind. Ready sales stayed near 1,200 deals, 35.3% fewer than a year ago.
A two-speed market: apartments down, villas up
The overall figure hides two opposite trends. Apartment deals fell 31.1% year on year to about 3,500, with both off-plan (about 2,700) and ready (about 800) lower. According to the source, the main reason is that fewer apartment projects were launched in 2026 than in 2025, not that buyers lost interest.
Villas and townhouses went the other way: about 2,350 deals, 89.4% more than a year ago. Off-plan villas and townhouses grew 153.4% to about 1,950 deals, on the back of more launches. The value of off-plan villa and townhouse sales rose 289% year on year, while the value of off-plan apartment sales fell 29%.
Volumes now follow launches: when developers release villas, villa sales jump; when fewer apartment towers come out, apartment sales fall.
For a buyer this is practical. Volumes now follow launches: when developers release villas, villa sales jump; when fewer apartment towers come out, apartment sales fall. The next quarters will depend on what developers bring to market, as much as on demand.
Where buyers buy
Demand is concentrated in a handful of districts. Al Reem Island and Yas Island together took 60.6% of apartment sales, and the five leading districts 83.4%.
| Al Reem Island | 1,200 |
|---|---|
| Yas Island | 920 |
| Al Saadiyat Island | 420 |
| Al Shamkhah | 197 |
| Al Raha | 181 |
Cavendish Maxwell, Quanta
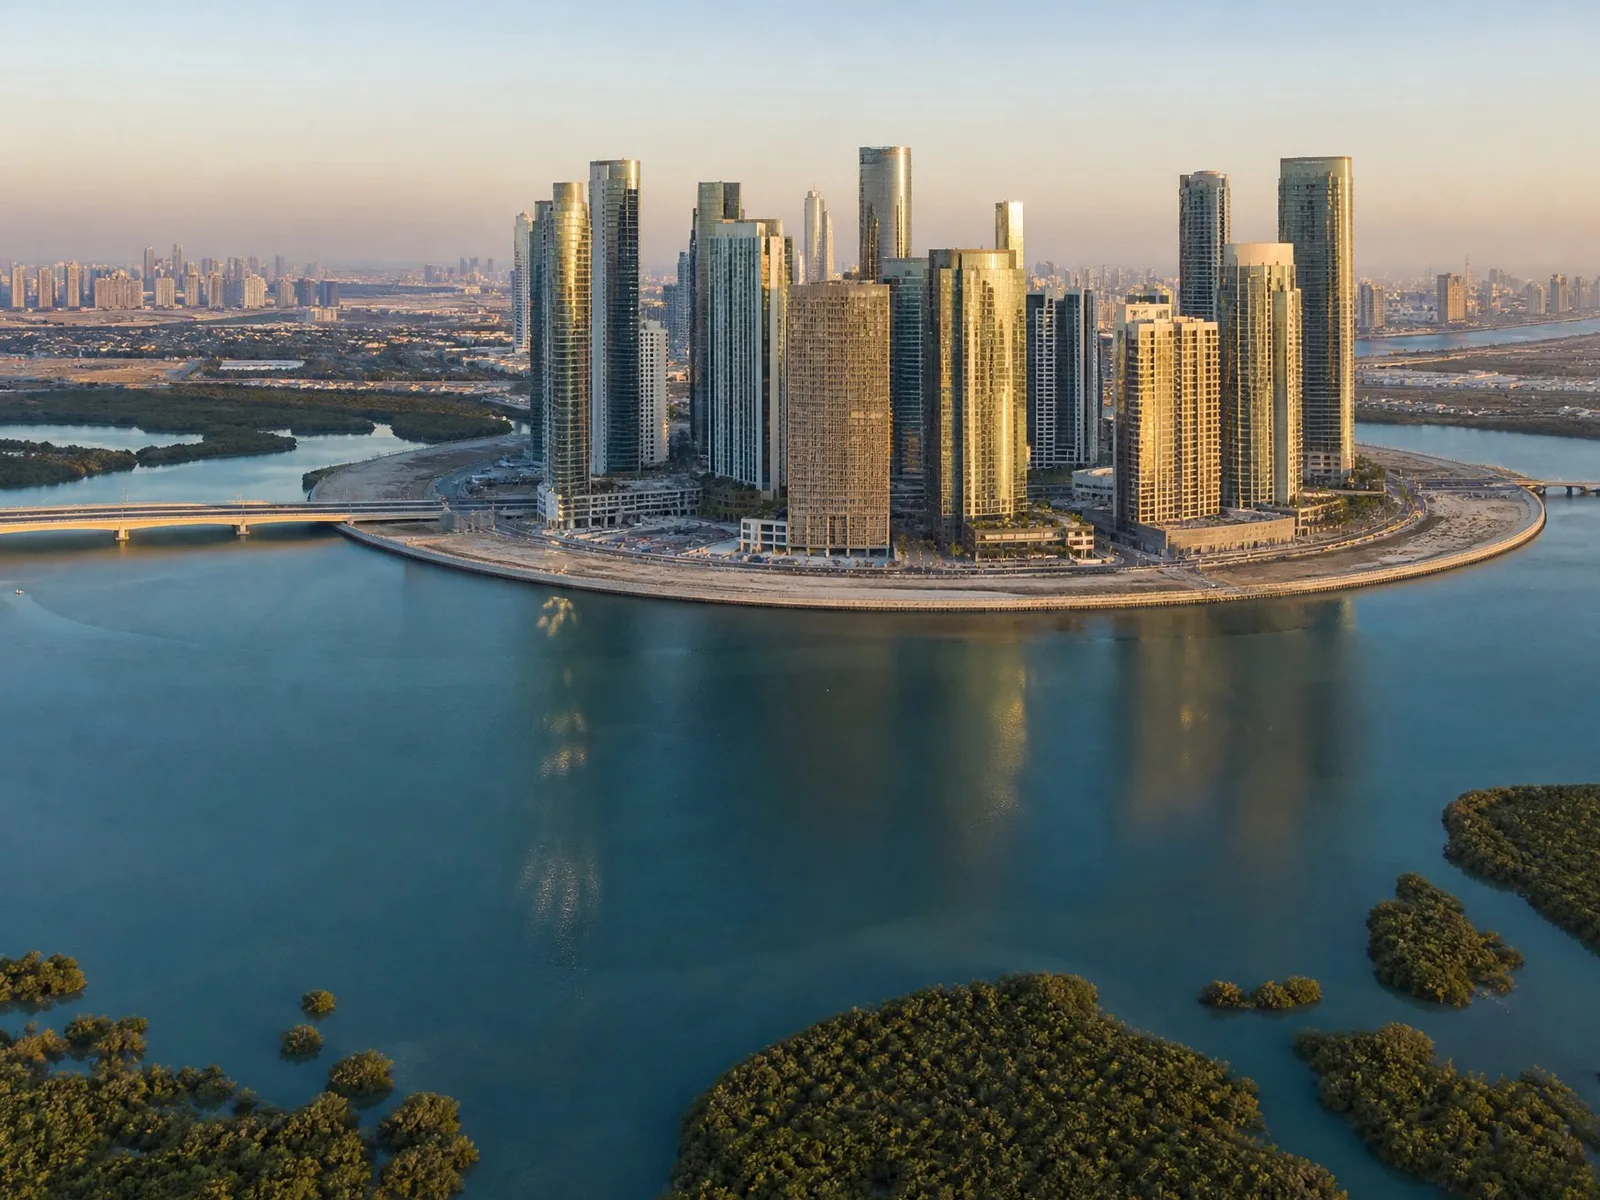
In villas the concentration is even stronger. Al Hudayriyat recorded about 1,070 deals, 45.5% of all villa and townhouse sales in the city; Hudayriyat Golf Estates alone accounted for 36.5%. Al Bahyah (191), Ghadeer Al Tayr (153), Ramhan Island (143) and Al Shamkhah (136) follow far behind.
Prices: still rising, more slowly
Fewer deals did not push prices down. Average apartment prices in Abu Dhabi rose 11% year on year and villa prices 8.9%, with every key district in positive territory. Growth is slower than in 2025, as buyers weigh the regional situation more carefully.
| Abu Dhabi average | 11% |
|---|---|
| Al Raha Beach | 11.1% |
| Al Reef | 10.5% |
| Al Reem Island | 10.1% |
| Yas Island | 8.4% |
Cavendish Maxwell
Villa prices varied more by district: Yas Island led with 10.9%, Saadiyat Island added 6.3%, Al Raha Gardens 5.7% and Al Reef 3.2%.
Rents under the freeze
- 3.5%apartment rents, change year on yearQ3 2026 · Cavendish Maxwell
- 1.8%villa rents, change year on yearQ3 2026 · Cavendish Maxwell
Rental growth has become modest. Yas Island showed the strongest apartment rent growth at 7.9% and Al Reem Island 5.5%; among villa communities Al Raha Gardens led with 5.1%. The rental freeze in Abu Dhabi limits how far landlords can raise rents, and the source sees early signs that it is starting to work.
With new supply concentrated in a few areas, tenants there will get more choice and landlords less room to raise rents. Over time the freeze may also widen the gap between new buildings and older stock, where quality and amenities will decide who finds tenants.
Supply: 38,800 homes on the way
About 9,900 homes were completed in Abu Dhabi City in 2026 by the end of September, and 5,500 more are scheduled by year-end. Judging by past delivery rates, only 1,700 to 3,300 of them are likely to be ready on time.
| Year | New homes | Total stock at year-end |
|---|---|---|
| 2025 | — | 317,900 |
| 2026, estimate | 9,900 completed + 5,500 scheduled | 333,400 |
| 2027, forecast | 14,600 | 347,900 |
| 2028, forecast | 24,200 | 372,100 |
About 14,600 homes are due in 2027 and 24,200 in 2028. If the pipeline is delivered in full, the city's housing stock would reach about 372,000 homes by the end of 2028. In practice part of it is likely to slip: rising construction costs and material sourcing may push some 2027–28 projects back.
The economy behind the numbers
The first half of 2026 was hard for the UAE economy: real GDP grew 0.4% year on year, with hospitality, transport, manufacturing and trade hit hardest by regional disruption. The third quarter looked better. The UAE PMI rose from 50.8 in June to 55.3 in August and September, with output and new orders growing.
Abu Dhabi is expected to do better than the wider economy. Fitch Ratings forecasts 3.7% GDP growth for the emirate in 2026 and 15.1% in 2027, on higher oil output and capital spending; the IMF expects the UAE economy as a whole to contract 3.9% in 2026 and rebound 7.7% in 2027. Business formation slowed: 9,600 new licences in the third quarter against 10,600 a year earlier.
What it means for buyers and investors
- Sales will follow launches and buyer confidence: watch which projects come out, not only the headline volume.
- Prices keep rising, but more slowly: a purchase is a bet on location and quality, not on the market lifting everything.
- Rent growth is capped by the freeze and by new supply, especially where completions cluster; check the yield of a specific building, not the city average.
- Older stock will compete with new buildings for tenants: well-located homes with good amenities hold up best.
Download the full report: 14 pages with the charts of sales, prices, rents and supply by district. If you want to go through the numbers for a specific purchase or sale in Abu Dhabi, our brokers will help.
Source: Cavendish Maxwell, “Abu Dhabi Residential Market Performance Q3 2026”; transaction data Quanta, supply Abu Dhabi Real Estate Centre and MEED Projects; macro data IMF, Fitch Ratings, S&P Global. Residential unit sales in Abu Dhabi City, excluding residential complexes, duplexes and penthouses. For information only; not investment, legal or financial advice.
Sources
- Cavendish Maxwell, Quanta
- Cavendish Maxwell, Quanta. Thousands of deals; value in AED billion
- Cavendish Maxwell
Written by
Inside EditorialMarket reviews and news by the Inside Realty team · 15 articles